Concentrates Are a Small Corner of the Ohio Market — but the Mix Is Changing Fast
Bloom's 2026 Ohio sales data shows concentrates holding steady at about 1 in 25 items sold, while live badder leads and rosin swings month to month.
By Jose Patino
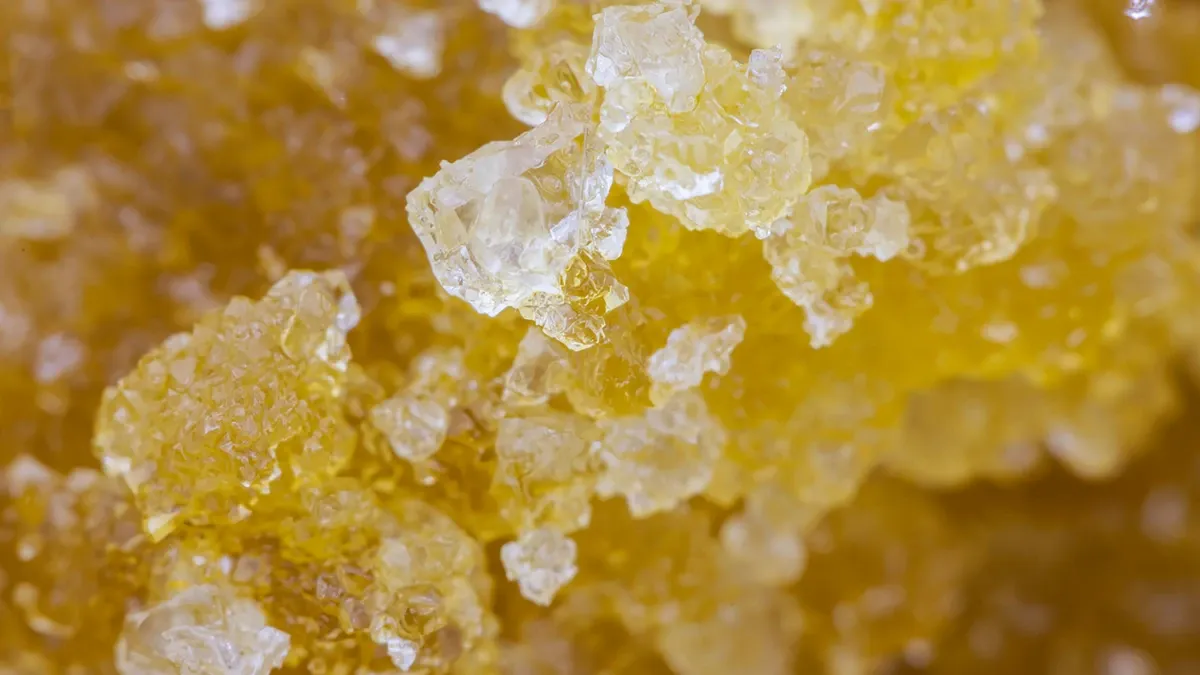
Concentrates have a reputation as the fastest-moving corner of the cannabis market. In Ohio, our sales data says otherwise.
Extracts have accounted for between 4.1% and 5.0% of everything sold at Bloom Cannabis dispensaries in every month of 2026 so far. That is roughly one item in twenty-five, and August (4.1%) landed just below where January started (4.2%). Eight months, no meaningful movement.
The flatness is the interesting part. Inside that steady slice, the mix changed a lot — and it changed in a direction worth knowing about if you shop the concentrate case.
Concentrates hold steady while flower gives up ground
The concentrate category has been remarkably stable. Everything around it has not.
- Flower fell from 33.2% of items sold in January to 28.9% in August — a loss of more than four percentage points.
- Vape climbed from 28.9% to 30.4%, and has outsold flower by unit count every month since May.
- Pre-rolls gained ground too, moving from 11.8% to 14.2%.
- Extracts stayed put at roughly 4% to 5% the entire time.
So the shift away from flower is real, but it is not going to concentrates. It is going to vapes and pre-rolls. Concentrate buyers look less like a growing wave and more like a consistent group that knows what it wants and keeps coming back for it.
Live formats now take about two-thirds of the concentrate counter
Group the live-material extracts together — live badder, live crumble and sugar, rosin, diamonds and sauce — and a clear pattern shows up.
In January, those formats made up 54.9% of concentrate sales. In February they jumped to 62.4%, and every month since has landed between 62% and 67%, averaging 63.8%.
Worth being precise about what that means: this was a step change early in the year, not a steady climb. Something moved in February and then held. Non-live formats — shatter, kief, dry-sift hash — have been sharing the remaining third ever since.
If the word “live” on a label has never meant much to you, it refers to when the plant was processed rather than how. Live products start from material that was frozen within hours of harvest instead of being dried and cured for days or weeks first. Curing drives off a portion of the plant’s volatile terpene content; freezing preserves more of it. That is the whole distinction, and it is why live products tend to carry a more pronounced aroma than their cured equivalents made from the same cultivar.
Live badder is the format Ohio keeps buying
One product type sat at number one in all eight months without exception. Live badder — sometimes labeled whipped extract or budder — took between 30.8% and 40.5% of concentrate sales each month, and 34.3% across the period overall.
August was its strongest month yet at 40.5%.
Badder is made from that same flash-frozen material, extracted and then whipped into a soft, opaque, cake-frosting texture. That texture is a large part of the appeal: it is easier to portion and handle than glassy formats, which matters if you are new to the category. Shatter, at the opposite end, has to be broken apart and tends to fragment when you do it.
Consistency at the top is itself a finding. Plenty of categories churn month to month depending on what dropped that week. Badder did not — it held first place through eight months of changing inventory, which suggests a genuine preference rather than a supply artifact.
Rosin is the volatile one
Rosin sits at number two overall at 22.2% of concentrate sales, but it does not sit still.
It started the year at 18.2% of the category, climbed to 29.0% by May — a 45% jump in units between the first and second quarters — then fell back to 17.1% in August, its lowest share of the year.
It is tempting to read that as a solventless surge, but the rest of the solventless numbers do not cooperate. Hash fell 32% and kief fell 22% over the same stretch that rosin was climbing. Rosin specifically has a devoted following in Ohio. Solventless as a whole does not appear to be taking over anything.
The practical version for shoppers: rosin availability swings more than most categories, and the swing looks more like supply than sentiment. Rosin is slower and more expensive to produce than solvent-based extracts, and pressing depends on getting starting material good enough to be worth pressing. If you buy it, it is worth checking the menu when a fresh batch lands rather than assuming it will be there next month.
What actually separates these formats
If the labels blur together at the counter, here is the short version. Potency ranges below are broad industry norms, not our menu — the certificate of analysis on the actual package is the number that counts.
| Format | How it’s made | Texture | Typical potency range | Share of Ohio concentrate sales |
|---|---|---|---|---|
| Live badder / whipped | Solvent extraction from flash-frozen fresh material, then whipped | Soft, opaque, frosting-like | ~60–85% THC | 34.3% |
| Rosin | Solventless — heat and pressure only | Ranges from sappy to badder-like | ~60–80% THC | 22.2% |
| RSO / FECO | Full-plant extraction, minimally refined | Thick, dark, syrupy | ~50–70% THC | 9.8% |
| Live crumble / sugar | Same as badder, textured differently during purge | Crumbly or granular | ~60–80% THC | 4.9% |
| Hash | Solventless — compressed trichomes | Pressed, pliable brick | ~40–60% THC | 3.1% |
| Shatter | Solvent extraction, purged without whipping | Hard, glassy, translucent | ~70–90% THC | 2.5% |
| Kief / sand | Solventless — sifted trichomes | Loose powder | ~20–60% THC | 2.2% |
| Diamonds & sauce | Crystallized THCa suspended in terpene-rich liquid | Crystals in viscous sauce | ~80–90%+ THC | 1.5% |
What this data doesn’t tell you
A few limits worth stating plainly, because they change how much weight these numbers can carry.
- About one in five concentrate items carries a generic extract tag rather than a specific format. That is 19.5% of the category we cannot break down, and it is large enough to move any of the rankings above.
- Diamonds and sauce shows zero-sale months in April and May, which almost certainly reflects what was available to stock rather than what anyone wanted. We left it out of the trend reading for that reason.
- These are unit counts, not dollars. Concentrates carry a higher price per item than flower, so the revenue picture looks different from the unit picture.
- Availability shapes demand. Nobody buys what is not on the shelf, and concentrate supply moves around more than flower supply does.
- This is Ohio only, across Bloom’s eight Ohio dispensaries, over eight months of 2026. It is not a national read.
New to concentrates?
If you are working out where to start, the format names matter less than two things on the label: the potency number and whether it was made from fresh-frozen or cured material. Our guide to cannabis concentrates walks through the categories in more depth, and if you are trying to sort out the two formats that dominate the Ohio numbers, we compared them directly in live resin vs. live rosin.
You can also see what is actually in stock right now in our roundup of the best marijuana concentrates in Ohio.
Browse concentrates and order online for pickup at any of our Ohio dispensaries.
For general information. This post isn't medical or legal advice. Cannabis rules differ between Ohio and Maryland and can change, so check with the Ohio Division of Cannabis Control or the Maryland Cannabis Administration. Talk to a healthcare provider before using cannabis for a medical condition. For adults 21+ and registered medical patients.
More from the Bloom blog.
News3 min read
The Bloom Cannabis Index: Ohio Market Report, Q2 2026
Our Q2 2026 Ohio report: vape overtakes flower, extracts hold their gains, and Northeast Ohio leads growth. Unit-volume trends from Bloom's dispensary data.
Jose PatinoAugust 25, 2026
News6 min read
Gummies, Chocolates, or Drinks? How Edible Preferences Actually Break Down
Gummies dominate, but second place is closer than you'd think. How edible format preferences actually split, and how to find the one that fits you.
Jose PatinoAugust 5, 2026
News6 min read
Federal Hemp & Delta-8: What P.L. 119-37 Could Mean for Shoppers
A new federal hemp law (P.L. 119-37) reshapes delta-8 in 2026. Here's what changes, which products are affected, and what it means for dispensary shoppers.
Jose PatinoJuly 27, 2026
Earn points, get the deals first.
Join Bloom Rewards free and start with 200 points, plus member-only deals and news from Bloom.
- 200 points for joining
- 1 point per $1 spent
- 100 points = $5
- Member-only deals and drops
Earn at any Bloom in Ohio or Maryland. Pick your store when you sign up.